Logo
Bảo hiểm tiền gửi Việt Nam
Deposit Insurance of Vietnam
  • Giới thiệu
    • Thông điệp của Chủ tịch Hội đồng quản trị Bảo hiểm tiền gửi Việt Nam
    • Tổng quan về Bảo hiểm tiền gửi Việt Nam
    • Chức năng, quyền và nghĩa vụ của Bảo hiểm tiền gửi Việt Nam
    • Cơ cấu tổ chức
      • Ban lãnh đạo qua các thời kỳ
      • Ban lãnh đạo hiện nay
      • Sơ đồ tổ chức
      • Mạng lưới Bảo hiểm tiền gửi Việt Nam
  • Dành cho người gửi tiền
    • Quyền và nghĩa vụ của người được bảo hiểm tiền gửi
    • Biểu tượng tham gia bảo hiểm tiền gửi
    • Danh sách tổ chức tham gia BHTG
    • Thủ tục trả tiền bảo hiểm
  • Dành cho tổ chức tham gia bảo hiểm tiền gửi
    • Biểu tượng tham gia bảo hiểm tiền gửi (Bản điện tử)
    • Thủ tục tham gia bảo hiểm tiền gửi
    • Quyền và nghĩa vụ của tổ chức tham gia bảo hiểm tiền gửi
    • Hệ thống quản lý thu thập thông tin (ICM)
  • Thư viện
    • Video
    • Văn bản
      • Văn bản pháp luật về BHTG
      • Văn bản liên quan
      • Văn bản do BHTGVN ban hành
  • Thông tin báo chí
  • Ấn phẩm
    • Bản tin bảo hiểm tiền gửi
    • Báo cáo thường niên
    • Ấn phẩm khác
  • Liên hệ
icon home Trang Chủ icon arrow Knowledge & Expertise

Deposit insurance policy: Strengthening depositors' confidence, increasing capital mobilization for people's credit funds

Thứ 6 , 02/04/2021
Deposit insurance (DI) is an effective tool of the State Bank of Vietnam (SBV) and the Government for ensuring the safety of credit institution (CI) operations and strengthening the confidence of depositors in the banking system,

thereby contributing to increasing the mobilization of  idle capital for improving the standard of living and economic development.  To clarify the role and effectiveness of DI policy, our reporter had an interview with Mr.  Nguyen Ngoc Tuan - Chairman of the Board of Directors of Nhon Hanh people’s credit fund (PCF), Binh Dinh Province.
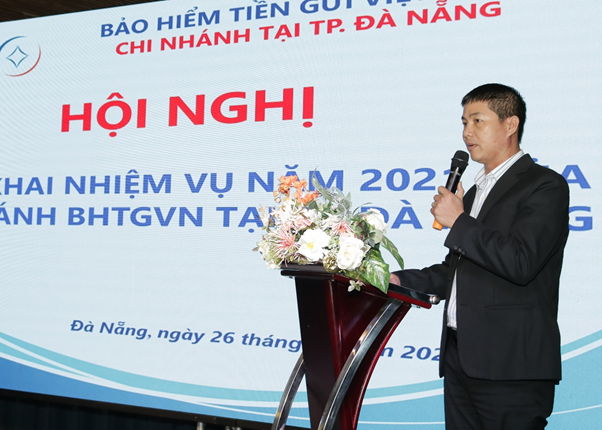
 Mr. Nguyen Ngoc Tuan - Chairman of the Board of Directors of Nhon Hanh PCF(Binh Dinh province)

Reporter: what do you think about the development of the PCF since its establishment in 1997?

Nhon Hanh PCF was licensed by the SBV’s Binh Dinh provincial branch in accordance with Decision No. 21/QD-NHNN dated May 30, 1997, and has been operating for 24 years. At the beginning, Nhon Hanh PCF faced many difficulties, especially in raising capital because people did not understand the operation of the PCF system in general and Nhon Hanh PCF in particular. Therefore, the amount of the PCF’s mobilized capital was very low, mainly relying on loans from the former Central PCF (currently, the Cooperative Bank).

Since then, in the Fund’s operation, everyone from the leadership to the officers and employees has always well observed the policies, guidelines and laws of the State; well implemented the instructions of the SBV; regularly monitored the developments of the local money market to offer mobilizing interest rates with suitable terms. Therefore, Nhon Hanh PCF has effectively attracted more idle capital from people each year, affirming its prestige and strengthening confidence of people when depositing money at the Fund.

As of December 31, 2020, Nhon Hanh PCF had 2,330 members with the total operational capital of more than VND 61 billion, charter capital of VND 1.4 billion and mobilized capital of VND 47 billion. Outstanding loans reached VND 54 billion. Profits after tax amounted to VND 460 million. The Fund has no overdue and bad debts.The credit quality is safe and effective. The Fund always fulfills its tax obligation to the State, and the rights of the staff and fund contributors are fully guaranteed.

Reporter: In the aforementioned process, how has  DI supported Nhon Hanh PCF?

I think that, for Nhon Hanh PCF to achieve the above results, the role of the Deposit Insurance of Vietnam (DIV) is indispensable. The Fund was granted a  DI participation certificate by the DIV with the commitment to protecting the legitimate rights and interests of its depositors. Thereby, people's confidence in Nhon Hanh PCF has been strengthened, thus helping the Fund to better mobilize capital.

In addition, the scale of Nhon Hanh PCF has been growing, contributing more positively to poverty reduction as well as to stabilizing and expanding production and business, creating jobs, reducing black credit and improving local people’s living standard.

The DIV’s examination and supervision are effective methods to minimize operational risks. To comply with the law on DI is also to protect the legitimate rights and interests of depositors, maintain the safe and healthy operation of Nhon Hanh PCF.

In addition, the DIV also regularly exchanges with and supports the Fund in effectively implementing the Regulation on information about insured deposits; implementing new regulations and guiding documents on DI.

Reporter: Do you have any recommendations on making DI policy more beneficial to depositors at Nhon Hanh PCF in particular and the PCF system in general?

Drawing on the characteristics of the PCF system, I would like to make some recommendations:

Currently, Nhon Hanh PCF in particular and PCFs in general mainly operate in rural areas. People’s understanding of banking and financial services and DI policy in these areas is still limited. Therefore, the DIV needs to actively collaborate with PCFs to disseminate information about DI policy so that people can better understand it, thereby strengthening depositors' confidence, helping to better mobilize idle capital from people, contributing to building new rural areas, and minimizing black credit in the areas.

PCFs operate for the purpose of supporting the community, so in addition to corporate income tax, the PCFs also have to pay many other fees. Therefore, it is suggested that DIV consider proposing the relevant authorities lower the DI premium rate for the PCF system.

Regarding the  DI coverage limit, according to the current regulations, the maximum amount of DI paid for all insured deposits (including principal and interest) of a depositor with an insured institution is up to  VND 75 million. This limit is far below the GDP per capita and the level recommended by international practices. In my opinion, it is necessary to soon increase the DI limit or insure 100% of deposits (if there appears a systematic risk).

Reporter: Thank you very much!
Các tin khác

Strengthening the role of deposit insurers in protecting financial consumers

Financial consumer protection is one of the important tools to increase people's access...

Changes in the role of deposit insurers in resolution of failed credit institutions and resolution tools after 2008 financial crisis

Deposit insurers (DIs) have often been established following financial and banking crises...

TIN ĐỌC NHIỀU
  • Phổ biến Luật Bảo hiểm tiền gửi năm 2025 tới Ngân hàng Hợp tác xã và quỹ tín dụng nhân dân tại tỉnh Hà Tĩnh
  • Khóa đào tạo Quy định pháp luật và quy định nội bộ của Bảo hiểm tiền gửi Việt Nam về hoạt động cho vay đặc biệt
  • Chi nhánh Bảo hiểm tiền gửi Việt Nam tại thành phố Hồ Chí Minh xây dựng kịch bản mô phỏng chi trả tiền bảo hiểm
  • Gợi ý tài liệu tham khảo Cuộc thi trực tuyến Tìm hiểu về bảo hiểm tiền gửi năm 2026
  • Chi nhánh Bảo hiểm tiền gửi Việt Nam khu vực Bắc Trung Bộ tổ chức hành trình về nguồn tại Hà Tĩnh
  • Thông cáo báo chí Cuộc thi trực tuyến “Tìm hiểu về Bảo hiểm tiền gửi năm 2026”
  • Bảo hiểm tiền gửi Việt Nam nâng cao năng lực bảo vệ người gửi tiền thông qua hoạt động hợp tác quốc tế
  • Hoàn thiện hành lang pháp lý, tăng cường bảo vệ người gửi tiền
  • Bảo hiểm tiền gửi Việt Nam tham dự Hội nghị thường niên và hội thảo quốc tế IADI 2026 tại Berlin, Đức
  • Tác phẩm của Bảo hiểm tiền gửi Việt Nam đoạt giải Khuyến khích Giải báo chí “Vì sự nghiệp Đại đoàn kết toàn dân tộc” lần thứ XVII
Quản lý ấn phẩm
Bản tin Bảo hiểm tiền gửi số 72 Quý II năm 2026
Bản tin Bảo hiểm tiền gửi số 71 Quý I năm 2026
	Bản tin Bảo hiểm tiền gửi số 70 Quý IV năm 2025
Bản tin Bảo hiểm tiền gửi số 69 Quý III năm 2025
Annual Report 2024
Bản tin Bảo hiểm tiền gửi số 68 Quý II năm 2025
Bản tin Bảo hiểm tiền gửi số 67 Quý I năm 2025
	Bản tin Bảo hiểm tiền gửi số 66 Quý IV năm 2024
Bản tin Bảo hiểm tiền gửi số 65 Quý III năm 2024
Annual Report 2023
Bản tin Bảo hiểm tiền gửi số 64 Quý II năm 2024
	Bản tin Bảo hiểm tiền gửi số 63 Quý I năm 2024
Bản tin Bảo hiểm tiền gửi số 62 Quý IV năm 2023
Annual Report 2022
Bản tin Bảo hiểm tiền gửi  số 61 Quý III năm 2023
 Bản tin Bảo hiểm tiền gửi  số 60 Quý II năm 2023
Bản tin Bảo hiểm tiền gửi  số 59 Quý I năm 2023
Bản tin bảo hiểm tiền gửi số 58 - Quý IV năm 2022
Bản tin bảo hiểm tiền gửi số 57 - Quý III năm 2022
Bản tin bảo hiểm tiền gửi số 56 - Quý II năm 2022

Chịu trách nhiệm nội dung website: ThS. Đặng Duy Cường

©Bản quyền 2026 được bảo lưu bởi Bảo hiểm tiền gửi Việt Nam

Lô D20, đường Tôn Thất Thuyết, phường Cầu Giấy, TP. Hà Nội.
(84-24)3974 2886
banbientap@div.gov.vn
  • Giới thiệu
    • Thông điệp của Chủ tịch Hội đồng quản trị Bảo hiểm tiền gửi Việt Nam
    • Tổng quan về Bảo hiểm tiền gửi Việt Nam
    • Chức năng, quyền và nghĩa vụ của Bảo hiểm tiền gửi Việt Nam
    • Cơ cấu tổ chức
      • Ban lãnh đạo qua các thời kỳ
      • Ban lãnh đạo hiện nay
      • Sơ đồ tổ chức
      • Mạng lưới Bảo hiểm tiền gửi Việt Nam
  • Dành cho người gửi tiền
    • Quyền và nghĩa vụ của người được bảo hiểm tiền gửi
    • Biểu tượng tham gia bảo hiểm tiền gửi
    • Danh sách tổ chức tham gia BHTG
    • Thủ tục trả tiền bảo hiểm
  • Dành cho tổ chức tham gia bảo hiểm tiền gửi
    • Biểu tượng tham gia bảo hiểm tiền gửi (Bản điện tử)
    • Thủ tục tham gia bảo hiểm tiền gửi
    • Quyền và nghĩa vụ của tổ chức tham gia bảo hiểm tiền gửi
    • Hệ thống quản lý thu thập thông tin (ICM)
  • Thư viện
    • Video
    • Văn bản
      • Văn bản pháp luật về BHTG
      • Văn bản liên quan
      • Văn bản do BHTGVN ban hành
  • Thông tin báo chí
  • Ấn phẩm
    • Bản tin bảo hiểm tiền gửi
    • Báo cáo thường niên
    • Ấn phẩm khác
  • Liên hệ